If your Apna Ghar loan has been approved but the money has not arrived, you are not alone and you are not necessarily rejected. By the end of September 2026, Rs76 billion had been disbursed to 13,214 borrowers under the Prime Minister’s Apna Ghar Scheme, while approved loans worth Rs350 billion were still waiting to be paid.
In short: Approval and payment are two different stages in this scheme. A bank can approve your eligibility, but it will release the money only after it has verified the property, completed the mortgage, and satisfied its disbursement conditions. When any one of those steps slows down, the whole file waits even if the borrower has done everything right.
Key Figures at a Glance
| Detail | Figure |
| Disbursed by end-September 2026 | Rs76 billion to 13,214 borrowers |
| Approved but not yet disbursed | Rs350 billion |
| Total approved financing at that point | Rs426 billion |
| Average loan disbursed | About Rs5.75 million per borrower |
| Government target for 2026-27 | Rs700 billion for 125,000 housing units |
These figures were shared with the Access to Finance Steering Committee, chaired by Finance Minister Muhammad Aurangzeb on 7 October 2026. Later October updates put total approvals even higher, at Rs448 billion for 75,198 loans, while disbursement stayed close to Rs76 billion. The queue was growing faster than payments.
What Do These Numbers Mean?
Demand is not the problem: outstanding housing finance grew from Rs323 billion in June 2026 to Rs426 billion by the end of September. Conversion is the problem: only about 18 percent of the approved Apna Ghar amount had reached borrowers, while about 82 percent was still in the pipeline.
The average loan of around Rs5.75 million fits the scheme first-time buyers, houses up to 10 marla or flats up to 1,500 sq ft, up to Rs10 million, 90 percent financing, 5 percent markup for 10 years, and up to 20 years’ tenure.
Why Approved Loans Are Stuck
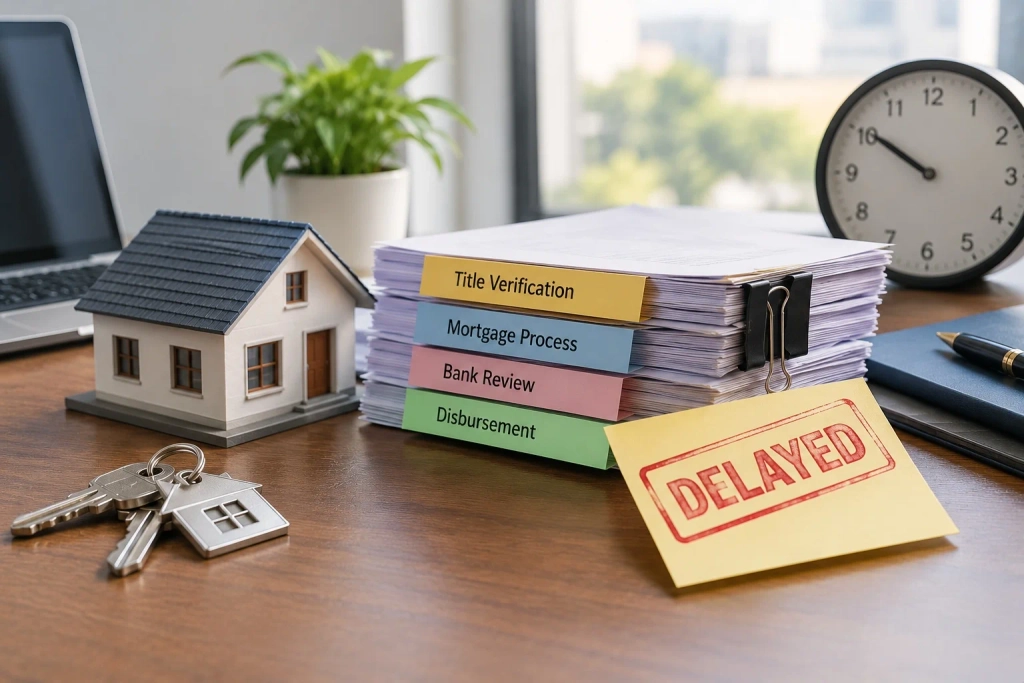
1. Approval is not disbursement. The State Bank’s 15-working-day rule applies to processing a complete credit application. It does not guarantee payment within 15 days. Verification, mortgage execution and disbursement conditions can still take longer.
2. Property title and mortgage are the real bottleneck. Before payment, the bank needs a clear, unencumbered title. It must check ownership, confirm there is no dispute or earlier charge, and register the mortgage. If a transfer letter, possession letter, site plan or mortgage permission is missing or disputed, the file stops. The Prime Minister directed officials to make it easier to obtain unencumbered title deeds a clear sign this step was causing delays.
3. Banks are approving faster than they can complete files. Meezan Bank is a good example. By the end of September it had approved about 6,880 cases worth around Rs49 billion, but only about 1,000 families had received money, worth Rs7.34 billion. In five weeks, approvals rose by more than 2,400 cases, while funded families rose by only about 350.
4. The supply side is also weak. A scheme that only funds buyers will soon run into a shortage of ready, legally clear homes. The Finance Minister therefore stressed the need for a proper builder-financing framework, so developers can also get finance to complete housing. Consultations on that framework were still under way in October.
5. Incomplete information still slows many cases. Some files wait because income needs review, or the property does not fully match scheme conditions. Total monthly repayments should generally stay within 65 percent of net disposable income, so a file that looks fine can still need extra checks.
The Five Documents and the New Rule
The October 2026 reform was meant to help. Under SBP Circular No. 06 of 2026, banks may require only five property documents, down from 25: the transfer letter, possession letter, site plan, mortgage permission letter and mortgage registration documents.
That is a major improvement, but it does not remove income and credit checks, or fix a disputed title overnight.
What the Government Has Asked Banks to Do
In October 2026, Prime Minister Shehbaz Sharif directed the State Bank of Pakistan and leading banks to accelerate disbursements, simplify procedures and remove bottlenecks, and to complete consultations by the end of October, including on developer financing. None of this releases a pending loan the next day, but it shows the delay is now treated as a delivery problem.
What to Do If Your Loan Is Approved But Not Paid
Do not assume silence means rejection, and do not pay anyone who promises to release your loan for a fee. Here is what to do instead:
- Ask your bank, in writing, which stage your file is at: approval, mortgage, verification or disbursement.
- Confirm your title is clear, mortgage registration is complete, and the five property documents match your CNIC and property record.
- If anything is pending from you, submit it in one complete set and keep copies of every submission.
- If the bank does not respond, check your status on apnaghar.gov.pk and use the State Bank’s Sunwai portal for a banking complaint.
If you are buying in a housing society, also confirm the society and plot record are clear before paying a seller in full. A loan approval does not protect you if the property later turns out to be disputed.
Frequently Asked Questions (FAQs)
1. How much has Apna Ghar paid so far?
By end-September 2026, Rs76 billion had been disbursed to 13,214 borrowers, while Rs350 billion in approved loans was awaiting disbursement.
2. Why is my approved Apna Ghar loan not disbursed?
Most commonly because mortgage registration, title verification or another disbursement condition is still pending. Approval means you are eligible; disbursement means the bank has completed all security and property checks.
3. Does the 15-working-day rule mean I must be paid in 15 days?
No. It relates to processing a complete credit application, not guaranteeing disbursement within 15 working days.
4. How can I check my Apna Ghar loan status?
Log in to apnaghar.gov.pk. For bank-related complaints, use the State Bank’s Sunwai portal.
5. Is this the same as Punjab’s Apni Chhat Apna Ghar scheme?
No. Apna Ghar is the federal scheme, while Apni Chhat Apna Ghar is Punjab’s separate programme with different terms and a different portal.
Conclusion
The Apna Ghar Scheme has not failed at approving loans. It is struggling at the last mile: turning an approval into money in a borrower’s hands. For applicants, the best approach is practical: know your file’s exact stage, complete the five documents correctly, keep your title clear, and follow up with your bank in writing.
Want to know more? Check out Apna Ghar Loan Now Needs Only 5 Documents (2026 Update).
Like, share and comment: Facebook, Instagram, Youtube and TikTok.


Join The Discussion